Hampton Roads Real Estate Blog & Local Market Insights
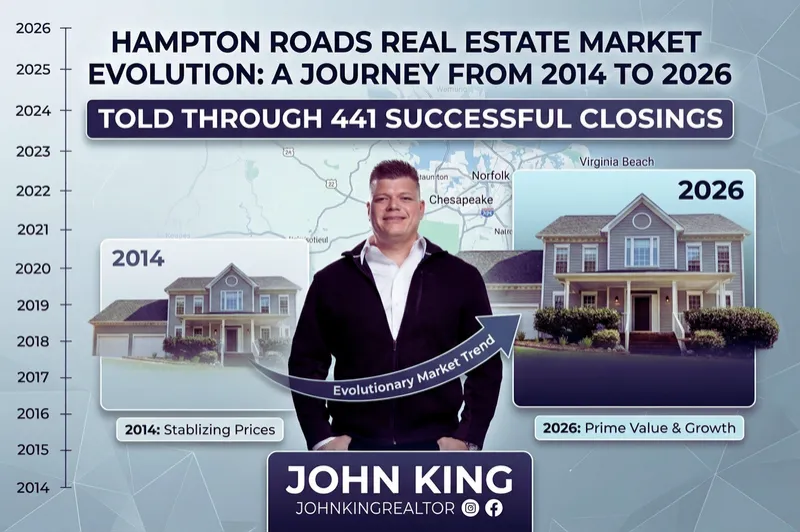
Written by John King, a U.S. Navy veteran and Berkshire Hathaway HomeServices RW Towne Realty REALTOR® with 441 closings across Hampton Roads, this library covers what buyers, sellers, and military families actually need to know about real estate in Virginia Beach, Norfolk, Chesapeake, and the surrounding 757.
Explore more than 200 original Hampton Roads real estate articles covering local neighborhoods, military PCS moves, VA loan strategy, home selling, waterfront property, market trends, and home buying — lessons drawn from more than 13 years of local transactions, not syndicated content.
Every guide is organized by topic below. Start with the cornerstone resources, browse a cluster, or scroll to the newest articles.
Start here
Start with these six cornerstone resources, then explore the supporting guides below.
Latest Hampton Roads Real Estate Articles
New guides and market updates are added every week. Newest first.
Retiring Military in Hampton Roads: Buy Now or Wait?
Retiring Military in Hampton Roads: Buy Your Forever Home Now or Wait?
You've got 20 years in. Maybe more. The retirement paperwork is on the horizon, and you're starting to look at the map and ask the bigger question. Where do we actually want to land?
If Hampton Roads keeps showing up on your shortlist, you're not alone. According to the U.S. Department of Veterans Affairs, this region sits in the middle of one of the largest active duty and military retiree populations in the United States. That doesn't happen by accident.
I'm John King. Navy veteran. Licensed agent with Berkshire Hathaway RW Towne Realty, serving all of Hampton Roads. Let's talk through the question you're actually asking. Should you buy your forever home now, or wait until your retirement date is closer?
Why Hampton Roads Keeps Pulling Retiring Military
Before we get into the timing question, it's worth being clear about why the region holds the attention of so many retiring service members in the first place.
Year-round coastal living without coastal-California or South-Florida prices. You get the beach, you get the bay, you get the climate, and you don't pay the premium that other coastal retiree markets demand.
Hampton VA Medical Center. A 432-bed teaching hospital that serves more than 50,000 veterans every year and is one of the fastest growing VA medical centers in the country. The VA also recently signed a 20-year lease for a new 182,000+ square foot outpatient clinic in Virginia Beach to expand access on the south side. For a retiring service member factoring in long-term healthcare logistics, the VA infrastructure here is real and growing.
Military community that doesn't disappear when you take off the uniform. With 19 military installations in the region and over 100,000 active duty personnel, your access to commissary, exchange, base privileges, and the broader veteran community stays close at hand.
A market with consistent demand. Hampton Roads has thousands of military families rotating in every year through PCS orders. That steady demand from incoming service members helps the local market hold value in ways markets without that constant turnover do not.
These are the factual, structural reasons the region attracts retiring military. They're also the reasons the math on a forever-home decision can get complicated, which is exactly why timing matters.
The Honest Case for Buying Now Rather Than Waiting
For most retiring service members within three years of their separation date, the planning math leans toward acting on the buy decision now rather than waiting. Here's why.
Inventory in the most desirable parts of Hampton Roads is limited. Waterfront property, single-story homes, established neighborhoods with mature landscaping. These do not get rebuilt. New construction in the region happens, but the homes most retirees are actually looking for already exist and are competed for every spring and summer when PCS season hits.
Interest rate timing is unpredictable. No one can reliably forecast where mortgage rates will be in 18 or 24 months. The seller in front of you today is real. The market a year from now is a guess.
Active duty BAH is often the strongest financing position you'll ever be in. Buying while still on active duty gives you BAH covering part or all of the mortgage and your full VA entitlement at your peak. Once you separate, your income picture changes. You may have retirement pay, you may have VA disability compensation, you may have a civilian job in the works. All of those count toward qualification, but the underwriting picture becomes more complex than it is while you're still on active duty.
Buying now lets you transition into the home, not into a hotel. Retirees who plan their forever-home purchase to close 30 to 60 days before the retirement date often save themselves the disorientation of an in-between period where they've left their old duty station, haven't bought yet, and are trying to make permanent decisions while temporarily housed.
That doesn't mean buying now is right for everyone. It means that for most retiring service members within their planning window, the structural advantages of acting earlier outweigh the perceived safety of waiting.
When Waiting Actually Makes More Sense
There are scenarios where waiting is the correct call:
You haven't decided where you're retiring. If Hampton Roads is one of three or four serious contenders and you haven't visited each, locked in a forever location, or had honest conversations with your spouse about it, do not buy yet. A forever home in the wrong region is the most expensive mistake you can make.
Your post-retirement income picture is uncertain. If your civilian employment plan isn't set, your VA disability rating is still pending, or your retirement pay is being calculated against an unusual service history, get those answers first. Buy when the income picture is clear, not when it's still forming.
You're more than three years out from your separation date. Buying a forever home five or six years before you actually retire creates a long carrying period where life can change in ways you can't predict. Tour orders. Family situations. Health considerations. The further out you are, the less the "buy now" math holds.
The right home isn't on the market yet and you can be patient. If you have a very specific set of requirements (single-story, water access, specific square footage, specific lot size) and the inventory isn't showing it, waiting for the right property is reasonable.
If any of those describe your situation, hold off. The wrong forever home is worse than no forever home.
Hampton Roads Areas Worth Knowing About
You have real options in Hampton Roads at almost every price point. Here are some neighborhoods and areas worth knowing about as you start exploring, organized by what makes each one distinctive. The right fit depends on your priorities for proximity to water, single-story home availability, walkability, or quiet established streets.
Virginia Beach Oceanfront and North End. Walkable to the sand, mix of older ranches and newer construction, distinctive coastal community character.
Great Neck Corridor including Alanton and Birdneck Point. Established Virginia Beach neighborhoods with waterfront access, mature landscaping, and a tight community feel. Price points generally start in the $700s and go well into the millions on the water.
Red Mill and Strawbridge. Established south Virginia Beach areas with strong infrastructure, single-story options, and walkable amenities.
Kings Grant, Little Neck, and Kempsville. More interior Virginia Beach options with established neighborhoods, mature trees, and price points often more accessible than the eastern oceanfront areas.
East Beach in Norfolk. Master-planned coastal neighborhood with new construction, beach access, and a walkable community design.
Chesapeake's Western Branch and Greenbrier. Larger lots, good infrastructure, easy access to multiple installations.
Williamsburg, Smithfield, and Suffolk's Harbour View. Quieter, less dense, often with more land for the price.
Atlantic Shores in Virginia Beach. A legally designated 55+ community with on-site amenities, healthcare integration, and a layout specifically built for active retirement living. If you're specifically looking for an age-designated community, this is the one to know about in the region.
The best way to find the right Hampton Roads home is to walk a handful of neighborhoods at different times of day, drive the routes you'd actually drive, and see what feels right. I'm happy to help you do that.
Using Your VA Loan Benefit in Retirement
This is one of the most under-used facts in military retirement planning. Your VA home loan benefit does not expire when you separate or retire. It is a lifetime benefit. According to the VA, eligibility remains intact whether you separated yesterday or 50 years ago, as long as you meet the original service requirements and have a satisfactory discharge.
Here's what that means in practical terms for a retiring service member buying a forever home.
You can use the VA loan in retirement. Zero down payment, no private mortgage insurance, competitive interest rates, all the same advantages you would have had on active duty. The benefit travels with you.
Your retirement pay and VA disability compensation count as qualifying income. Lenders evaluate retirement and disability income as stable, durable income for VA loan qualification, often more favorably than civilian wage income because there's no employment risk attached.
If you have a service-connected disability rating, you may be exempt from the VA funding fee. Veterans who receive VA compensation for a service-connected disability are exempt from paying the funding fee on a VA loan. On a $500,000 home, that's potentially several thousand dollars saved at closing. The exemption status appears directly on your Certificate of Eligibility.
Your entitlement may need to be reset depending on your situation. If you currently own a home with a VA loan attached and you're planning to sell that home as part of your retirement move, your full entitlement gets restored once the loan is paid off and the property is sold. If you're keeping a home as a rental and using your VA loan again on the new purchase, you'll be working with partial entitlement, which can affect how much you can borrow without a down payment. A local VA-savvy lender can pull your current entitlement position and tell you exactly where you stand before you write any offers.
Surviving spouses of certain veterans may also qualify. If you're reading this on behalf of a spouse who has lost their service member, the VA does extend home loan eligibility to qualifying surviving spouses under specific conditions.
The bottom line on the VA loan in retirement: it's one of the most powerful financial tools you've earned, and most retiring service members under-use it because they assume the benefit was tied to active duty. It wasn't. It still isn't.
How to Actually Make the Decision
When I sit down with a retiring service member, here's the order I work through:
The where question. Hampton Roads or somewhere else? If Hampton Roads is the answer, what part of the region matches your actual life? Distance to the VA, distance to base, distance to family, distance to water if that matters.
The when question. What's your retirement timeline? How does that line up with selling your current home (if you have one), pulling your COE, getting pre-approved, and finding the right property?
The how question. Are you using a VA loan, and what's your entitlement position? Are you planning to keep an existing home as a rental? What's your post-retirement income picture going to look like for underwriting?
The what question. What does the home actually need to be? Single-story or two-story? Yard or low maintenance? Distance from neighbors or community feel? Square footage and bedroom count?
By the end of that conversation, the answer becomes clearer. Sometimes it's buy now. Sometimes it's wait until a specific milestone. Either way, you walk out with a real plan instead of a guess.
Bottom Line
Hampton Roads has earned its reputation with retiring military for real, structural reasons. Coastal living, growing VA infrastructure, an active military community, and a market that holds value because demand never goes away.
For most retiring service members within three years of their separation date, the planning math leans toward acting on the buy decision sooner rather than later. Inventory is limited, rate timing is unpredictable, and your VA loan benefit is a powerful financial tool that you've already earned.
But the right answer for your forever home depends on your specific situation, your specific timeline, and your specific priorities. There's no formula that gives the same answer to every retiring service member.
If you've got 20 years in and you're trying to figure out whether Hampton Roads is the right call and whether now is the right time, let's get on a call. I'll walk through your situation, run the numbers honestly, and give you a straight read.
I'm not hard to find.
When it's time to talk real estate, you know who to call.
If orders have you headed this way, this guidance is built on the 13 year Hampton Roads transaction study, and you can browse all my Hampton Roads neighborhood guides.
Before you decide to buy now or wait, calculate your cost of waiting with the H.E.L.M. Check, which projects 6, 12 and 24 months under assumptions you choose.
About the Author
John King is a Navy veteran and licensed real estate agent with Berkshire Hathaway RW Towne Realty, serving Hampton Roads including Virginia Beach, Norfolk, and Chesapeake. Known for straightforward approach and market expertise.
📞 757-270-3994 📧 [email protected] 🌐 www.757King.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
Related guides from John King
Written by John King, Navy veteran & REALTOR®, Berkshire Hathaway HomeServices RW Towne Realty · (757) 270-3994 · About John

Why these guides are different
Every article here is written by one local agent from his own transaction record, not by a content farm. The numbers below are the basis for the advice.
John King is a former Navy Machinist Mate and a licensed Virginia REALTOR® with Berkshire Hathaway HomeServices RW Towne Realty in Virginia Beach. Licensed since 2013, he has logged 441 closings across Virginia Beach, Norfolk, Chesapeake, Suffolk, Hampton, and Newport News, and specializes in military PCS relocation, VA loans, and waterfront property. He holds a 5.0 Google rating across 117 reviews and has earned the HRRA Circle of Excellence every year since 2015.
About John King See the transaction studyCommon questions about this library
Tap a question to expand it.
What is the Hampton Roads Real Estate Blog?
Which Hampton Roads neighborhoods are closest to each base?
How do VA loans work when buying in Virginia Beach or Norfolk?
What is the Hampton Roads real estate market like right now?
Should I buy or rent during a PCS to Hampton Roads?
Ready to talk about your move?
Reading is a good start. A 15-minute conversation with a local agent who has logged 441 closings in Hampton Roads is a better one.
Prefer to talk? Call or text John at (757) 270-3994.
441 Closings
Client-side closings across Hampton Roads since 2014.
189 VA-Financed Sales
Direct experience with military and veteran buyers.
270 Subdivisions
Experience spread across the whole region.

FOLLOW US


COMPANY
CUSTOMER CARE
LEGAL
Copyright 2026 John King | KingRealtor757. All Rights Reserved. Equal Housing Opportunity. REALTOR(R). Virginia License 0225211050.