Hampton Roads Real Estate Blog & Local Market Insights
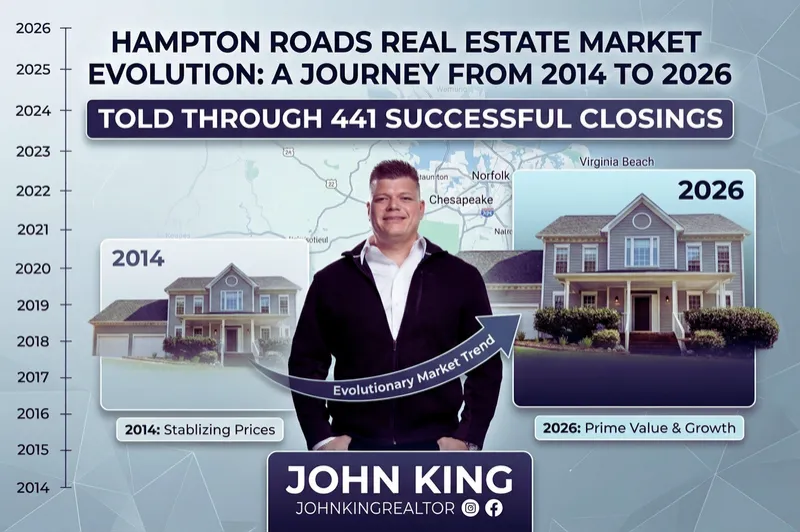
Written by John King, a U.S. Navy veteran and Berkshire Hathaway HomeServices RW Towne Realty REALTOR® with 441 closings across Hampton Roads, this library covers what buyers, sellers, and military families actually need to know about real estate in Virginia Beach, Norfolk, Chesapeake, and the surrounding 757.
Explore more than 200 original Hampton Roads real estate articles covering local neighborhoods, military PCS moves, VA loan strategy, home selling, waterfront property, market trends, and home buying — lessons drawn from more than 13 years of local transactions, not syndicated content.
Every guide is organized by topic below. Start with the cornerstone resources, browse a cluster, or scroll to the newest articles.
Start here
Start with these six cornerstone resources, then explore the supporting guides below.
Latest Hampton Roads Real Estate Articles
New guides and market updates are added every week. Newest first.
VA Loan Entitlement: Full vs. Partial Explained
In short: Full entitlement means no loan limit: lenders can qualify you for zero down at any price point. Partial entitlement, usually from an active VA loan or a past default, caps your zero down buying power. This guide shows how to check which one you have and how to restore it.If you are a veteran or active duty service member buying a home in Hampton Roads, your VA loan entitlement is one of the most important things to understand before you start shopping. Whether you have full entitlement or partial entitlement changes how much you can borrow, whether you need a down payment, and how competitive your offer can be in markets like Virginia Beach, Norfolk, and Chesapeake.
What Is VA Loan Entitlement?
VA loan entitlement is the amount the Department of Veterans Affairs guarantees on your home loan. It is what allows VA lenders to offer zero down payment financing without requiring private mortgage insurance. The amount of entitlement you have available directly affects your buying power.
There are two types: full entitlement and partial entitlement. Knowing which one you have before you start house hunting in Hampton Roads can be the difference between writing a competitive offer and missing out on the home you want.
What Full VA Entitlement Means
Full entitlement means you have no VA loan limits and no down payment is required based on what your lender approves you for. As long as your income, credit, and debt to income ratio support the loan amount, you can buy a home in Hampton Roads with zero down.
You typically have full entitlement if you have never used your VA loan before, if you previously used your VA loan and have since paid it off and sold the property, or if you had a previous VA loan foreclosure but have repaid the VA in full.
For Hampton Roads buyers, full entitlement is a significant advantage. Virginia Beach, Norfolk, and Chesapeake see steady demand from military families, and being able to write a zero down offer keeps you competitive against conventional buyers.
What Partial VA Entitlement Means
Partial entitlement means a portion of your VA loan benefit is currently in use or otherwise tied up. This usually happens when you already have an active VA loan on another property, when you sold a home previously financed with a VA loan but did not restore your entitlement, or when you had a short sale or foreclosure on a previous VA loan.
With partial entitlement, you may face VA county loan limits in your area, and you may need to make a down payment depending on the price of the home you want to buy. The down payment is calculated based on the difference between your remaining entitlement and the loan amount, not the full purchase price.
This matters in Hampton Roads because home prices in certain neighborhoods can push above the standard county loan limits. If you have partial entitlement, your lender will calculate exactly how much you may need to bring to closing.
Why You Need to Know Before You Start Shopping
Walking into the Hampton Roads market without knowing your entitlement status puts you at a disadvantage. Sellers in competitive military markets often choose between offers within hours or days. If you submit an offer assuming zero down and later discover you have partial entitlement, the financing math changes and the deal can fall apart.
A local lender who specializes in VA loans can pull your Certificate of Eligibility and tell you exactly where you stand. From there, you and your real estate agent can build a buying strategy that fits your actual entitlement, your budget, and the homes you want to compete for.
Common Questions About VA Loan Entitlement
How do I know if I have full or partial VA entitlement?
Your lender can pull your Certificate of Eligibility from the VA, which shows your entitlement status. You can also request your COE directly through the VA website or through eBenefits.
Can I use my VA loan more than once?
Yes. The VA loan benefit can be used multiple times throughout your life. If you have paid off a previous VA loan and sold the home, you can request entitlement restoration to return to full entitlement.
Do I need a down payment with partial entitlement?
It depends on the price of the home and how much remaining entitlement you have. If the loan amount exceeds your available entitlement combined with the VA county loan limit, you may need a down payment for the difference.
What is entitlement restoration?
Entitlement restoration is the process of recovering your full VA loan benefit after you have paid off a previous VA loan and sold the property. It allows you to use your full entitlement again on a new home purchase.
The Hampton Roads Advantage
Hampton Roads is one of the most VA loan friendly markets in the country. Local lenders, agents, and title companies handle VA transactions every day. Working with professionals who understand both your entitlement and the local market gives you the strongest possible position when it comes time to make an offer.
PCSing to or from Hampton Roads? I base all of this on real deals I have documented start to finish.
About the Author
John King is a Navy veteran and licensed real estate agent with Berkshire Hathaway RW Towne Realty, serving Hampton Roads including Virginia Beach, Norfolk, and Chesapeake. Known for a straightforward approach and deep market expertise.
📞 757-270-3994 📧 [email protected] 🌐 www.757King.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
Can You Use a VA Loan More Than Once?
Yes, and there is no lifetime cap. Every time you pay off a VA loan and sell that home, your full entitlement is restored and you can use the benefit again exactly as you did the first time. You may also be able to use remaining entitlement on a second property while still owning the first, which matters for families relocating on orders, moving up, or buying a home to live in while keeping the previous one as a rental. The key is knowing how much entitlement is in use and how much remains, which your Certificate of Eligibility shows and which an agent who works VA transactions every week can walk you through.
Your VA Benefit Never Expires
It does not matter whether you separated last year or twenty years ago. If you earned the benefit, it is still yours, with no deadline and no window that closes. Most veterans do not know that, and many who used it once assume it is gone. If you have been sitting on the benefit or think you used it up, there is a good chance you have more options than you think.
What the VA Loan Actually Gives You
Zero down payment: finance 100 percent of the purchase price where conventional loans want 3 to 20 percent down.
No private mortgage insurance, ever: hundreds of dollars a month that conventional buyers with less than 20 percent down cannot avoid.
Competitive rates: the federal guarantee lowers lender risk, and VA rates are consistently among the lowest available.
Closing-cost limits: the VA caps what you can be charged and lets the seller pay certain fees on your behalf.
No prepayment penalty: pay it off early without penalty, which matters when orders arrive and you need to sell.
Eligibility runs through service history: active-duty members with at least 90 continuous days, veterans meeting minimum service requirements for their era, Guard and Reserve members meeting service requirements, and surviving spouses of members who died in the line of duty or from a service-connected disability. The Certificate of Eligibility confirms it, and most buyers can pull it quickly through the VA's online system.
Why Hampton Roads Is One of the Best VA Markets in the Country
Because of the sheer volume of military buyers here, sellers and listing agents near the bases are used to VA offers, and the stigma VA loans carry in other markets is far weaker. They know military buyers are motivated, qualified, and serious, and that VA transactions close. Still, a VA pre-approval is not the same as a competitive VA offer. In multiple-offer neighborhoods near NAS Oceana, Naval Station Norfolk, and JEB Little Creek, the difference is how the offer is written: addressing appraisal gaps, inspection contingencies, and possession timelines without waiving protections you are entitled to, and walking into the VA appraisal knowing which property conditions can trigger issues before the offer is submitted. Zero down does not mean zero leverage; it means you need an agent who knows how to use it.
Related guides from John King
Written by John King, Navy veteran & REALTOR®, Berkshire Hathaway HomeServices RW Towne Realty · (757) 270-3994 · About John

Why these guides are different
Every article here is written by one local agent from his own transaction record, not by a content farm. The numbers below are the basis for the advice.
John King is a former Navy Machinist Mate and a licensed Virginia REALTOR® with Berkshire Hathaway HomeServices RW Towne Realty in Virginia Beach. Licensed since 2013, he has logged 441 closings across Virginia Beach, Norfolk, Chesapeake, Suffolk, Hampton, and Newport News, and specializes in military PCS relocation, VA loans, and waterfront property. He holds a 5.0 Google rating across 117 reviews and has earned the HRRA Circle of Excellence every year since 2015.
About John King See the transaction studyCommon questions about this library
Tap a question to expand it.
What is the Hampton Roads Real Estate Blog?
Which Hampton Roads neighborhoods are closest to each base?
How do VA loans work when buying in Virginia Beach or Norfolk?
What is the Hampton Roads real estate market like right now?
Should I buy or rent during a PCS to Hampton Roads?
Ready to talk about your move?
Reading is a good start. A 15-minute conversation with a local agent who has logged 441 closings in Hampton Roads is a better one.
Prefer to talk? Call or text John at (757) 270-3994.
441 Closings
Client-side closings across Hampton Roads since 2014.
189 VA-Financed Sales
Direct experience with military and veteran buyers.
270 Subdivisions
Experience spread across the whole region.

FOLLOW US


COMPANY
CUSTOMER CARE
LEGAL
Copyright 2026 John King | KingRealtor757. All Rights Reserved. Equal Housing Opportunity. REALTOR(R). Virginia License 0225211050.