Hampton Roads Real Estate Blog & Local Market Insights
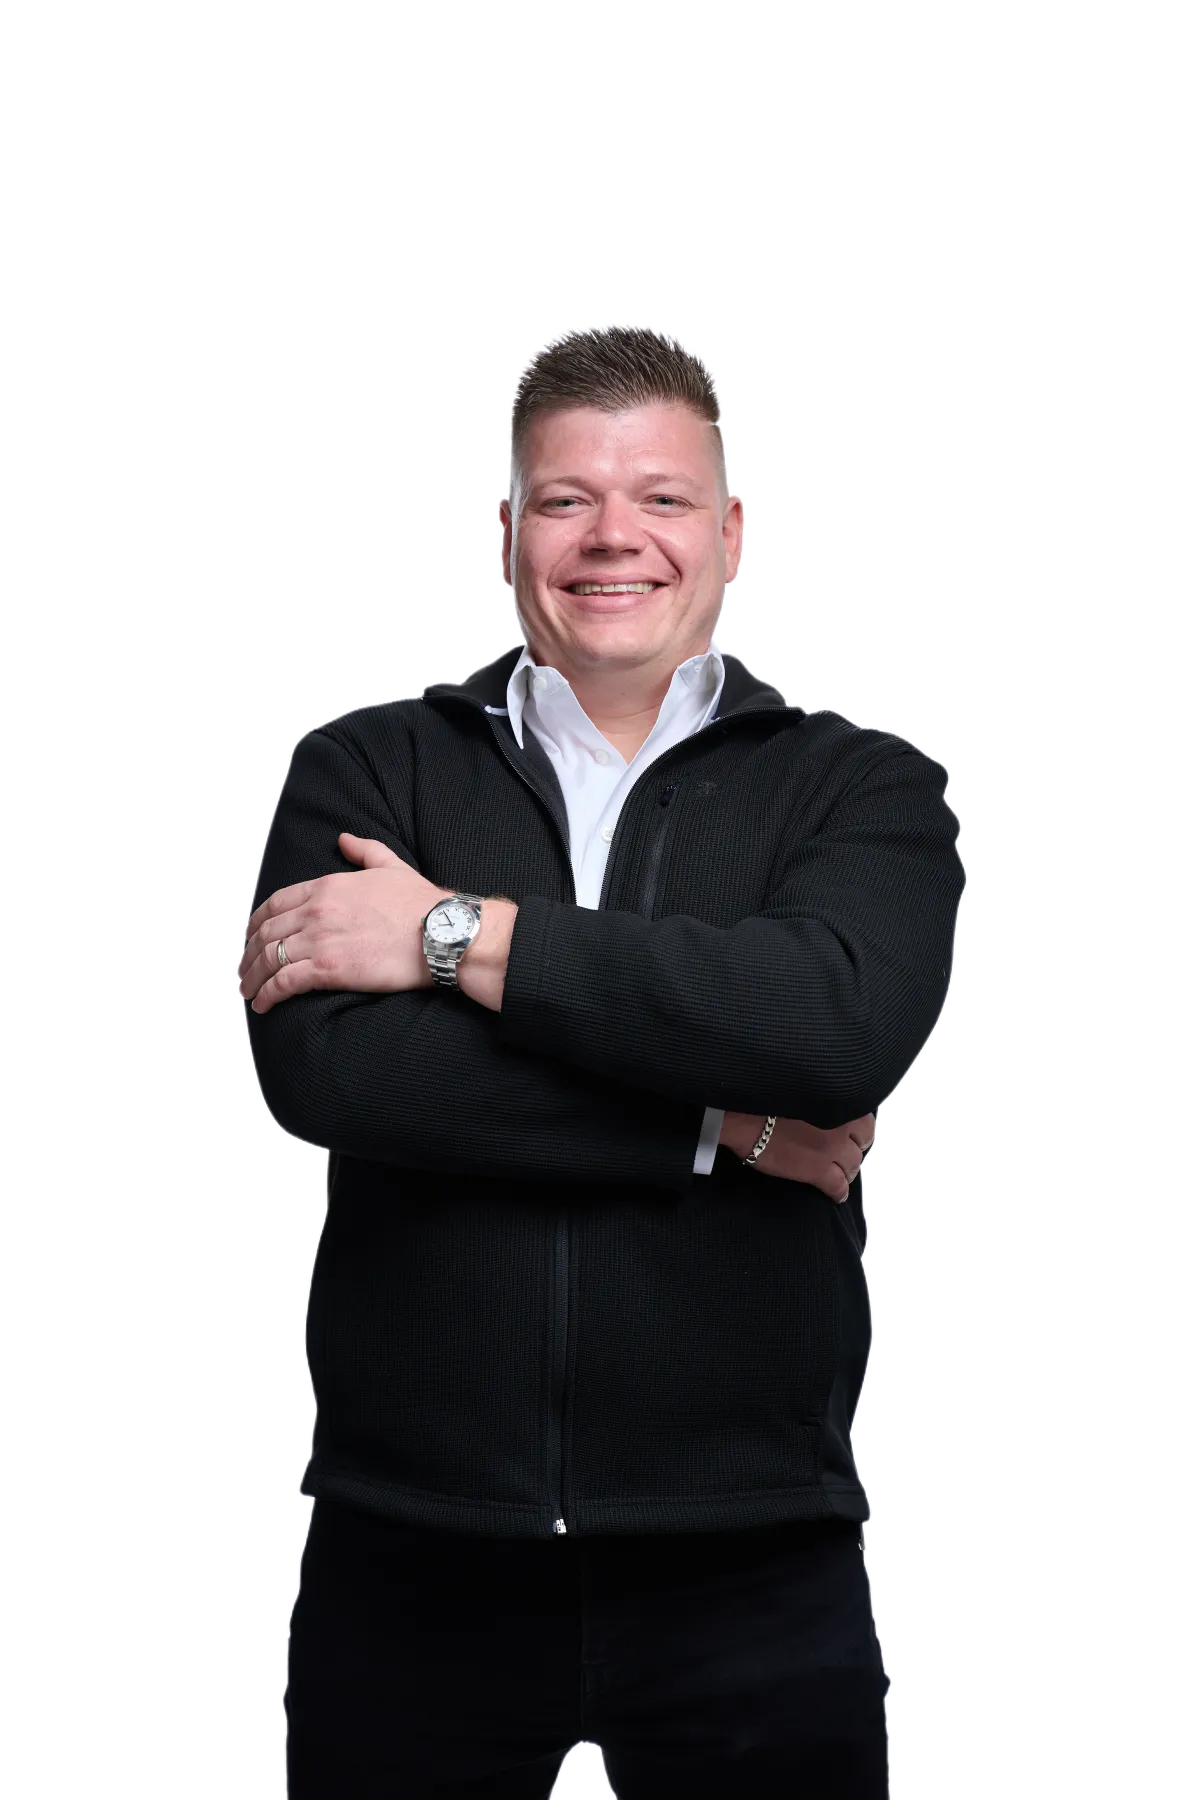
Written by John King, a U.S. Navy veteran and Berkshire Hathaway HomeServices RW Towne Realty REALTOR® with 441 closings across Hampton Roads, this library covers what buyers, sellers, and military families actually need to know about real estate in Virginia Beach, Norfolk, Chesapeake, and the surrounding 757.
Explore more than 200 original Hampton Roads real estate articles covering local neighborhoods, military PCS moves, VA loan strategy, home selling, waterfront property, market trends, and home buying — lessons drawn from more than 13 years of local transactions, not syndicated content.
Every guide is organized by topic below. Start with the cornerstone resources, browse a cluster, or scroll to the newest articles.
Start here
Start with these six cornerstone resources, then explore the supporting guides below.
Latest Hampton Roads Real Estate Articles
New guides and market updates are added every week. Newest first.
PCS Orders to Hampton Roads? Make This Call First | 757King
PCS Orders to Hampton Roads? Make This Call First
You just got PCS orders to Hampton Roads. Maybe Virginia Beach, maybe Norfolk, maybe Chesapeake. The clock starts the second the orders come down, and there's a stack of things you're already mentally tackling. Movers. Housing office. School research. Selling your current home. Figuring out what to keep and what to leave behind.
Here's the move most military families get wrong. They start with movers. They start with the housing office. They start with Zillow.
The first call should be different.
I'm John King. Navy veteran, licensed agent with Berkshire Hathaway RW Towne Realty serving all of Hampton Roads. Here's the order I tell every PCS family to follow, and why doing it in this exact sequence puts you in a completely different position when you actually start writing offers.
Step One: Connect With a Real Estate Agent Who Has Actually Closed VA Loans
Not an agent who says they "work with military buyers." Not an agent whose website has a flag on it. An agent who has actually closed VA loan transactions in the Hampton Roads market, recently, and can tell you about the specific quirks that come with VA financing here.
VA loans aren't conventional loans. The appraisal process is different. The funding fee math is different. The seller concession rules are different. The repair and inspection requirements are different. Termite letters are required. Wood rot gets flagged. Chipped paint on a pre 1978 home becomes an issue. Sellers in this market know all of this, and a listing agent who's seen a VA deal fall apart at the appraisal table will scrutinize every VA offer they receive.
If your buyer's agent doesn't know the VA loan landscape cold, you're already at a disadvantage before the offer is even written.
What to ask before you hire:
How many VA loan transactions have you closed in Hampton Roads in the last 12 months? Ask for a number.
What's your relationship with local VA savvy lenders? Out of state lenders cause more VA closing delays than any other single factor.
How do you handle a Tidewater initiation when an appraisal comes in low? If they don't know what a Tidewater is, keep looking.
Are you a veteran, or have you worked extensively with veterans? Not required, but it changes the conversation.
Step Two: Get Pre Approved With a Local Lender
This is where most buyers cut corners and pay for it later.
Pre qualified and pre approved are not the same thing. They sound the same. Some lenders even use the terms interchangeably. They're not.
Pre qualified means you had a conversation with a loan officer. You told them your income, your debts, your rough credit picture. They plugged numbers into a calculator and gave you a ballpark figure. No documents were verified. No credit was pulled in many cases. The letter is essentially a guess based on what you said about yourself.
Pre approved means the lender has actually verified everything. Your Certificate of Eligibility is pulled. Your pay stubs, W2s, and tax returns are reviewed. Your bank statements are documented. Your credit is run with a hard inquiry. Your debt to income ratio is calculated against real numbers. Your residual income (a VA specific requirement) is checked against the regional standard for your family size.
The pre approval letter you walk away with reflects a real loan, real numbers, and real underwriting. Not a guess.
Why a Local Lender Matters (And Why I Have a Specific One I Send Veterans To)
You can technically use any lender licensed in Virginia. You shouldn't.
Local Hampton Roads lenders close VA loans here every day. They know the appraisers. They know the title companies. They know which neighborhoods have HOA quirks that slow down funding. They answer the phone on weekends during PCS season. They show up at closings. When a problem hits at week six of a 30 day close, a local lender solves it. An online lender 2,000 miles away sends an email that gets returned 18 hours later because of time zone differences and call center routing.
I've watched too many PCS deals collapse in the final week because the buyer's lender was a name they saw in a Google ad. Don't be that buyer.
Here's where I'll be straight with you. I have a veteran loan officer I've been working with for over eight years. He's a veteran himself, with decades of experience specifically in VA loan products. When a veteran or active duty buyer calls me, they're getting a veteran real estate agent plus a veteran loan officer who knows VA financing inside out. That's a combination most teams in Hampton Roads simply can't match.
You are absolutely free to use whatever lender you want. I'll work with anyone, and I'll work hard to make your transaction smooth regardless. But when buyers use the loan officer I trust, the deal moves faster, hits fewer surprises, and closes cleaner. There's no kickback, no referral fee, no financial arrangement on my end. It's just experience working with experience.
If you're heading into a Hampton Roads VA purchase and you don't already have a lender, ask me. I'll make the introduction, you'll have a conversation, and you decide from there.
What a Fully Underwritten Pre Approval Actually Means
Standard pre approval already puts you ahead of pre qualified buyers. Fully underwritten or certified pre approval puts you in a different category entirely.
With a fully underwritten pre approval, your file has been reviewed by an actual underwriter, not just a loan officer running the automated system. Your income, employment, credit, and assets have been documented and approved. The only remaining items are the property itself (appraisal, title, insurance) and any final updates to your file before closing.
In a multiple offer situation, that letter signals to the listing agent that you're as close to a cash buyer as a financed buyer can be. The seller's biggest fear with VA buyers (the deal falling apart at financing or appraisal) gets cut roughly in half. Your offer reads stronger on paper, which is exactly what the seller is looking at when they make their decision.
Not every lender offers fully underwritten pre approval. Ask. If they don't, find one who does.
Why This Matters in the Hampton Roads PCS Market
PCS season in Hampton Roads runs roughly April through September, with the heaviest activity from May through August. During those months, well priced homes in popular military neighborhoods can go under contract in hours. Not days. Hours.
When a seller is sitting on three offers at once, they're not flipping a coin. They're looking at:
The offer price.
The buyer's loan type and pre approval strength.
The earnest money deposit.
The closing timeline.
The contingencies.
The pre approval letter is one of the first things the listing agent reads. A pre qualified buyer's letter and a fully underwritten VA pre approval letter look very different on paper, and the listing agent flags that difference for the seller before they ever discuss price.
If you show up to a multiple offer with a generic pre qualification letter from an online lender, your offer is at the bottom of the pile before negotiations even start. If you show up with a fully underwritten pre approval from a local Hampton Roads VA lender, you're in the conversation no matter what your offer price is.
The Sequence That Actually Works
Here's the order I tell every PCS buyer to follow:
Connect with a Hampton Roads agent who closes VA loans regularly. Have a real conversation about your timeline, your priorities, and the specific base or area you're heading to.
Get referred to two or three local VA savvy lenders. Interview them. Pick one.
Submit your full document package to your chosen lender and ask specifically for a fully underwritten or certified pre approval.
Pull your Certificate of Eligibility (your lender can do this for you in most cases through the VA's automated system).
Once your pre approval is in hand, start showing schedule with your agent. Live, virtual, or both depending on where you're stationed.
When you find the right home, write an offer that reflects the strength of your financing. Don't apologize for using a VA loan. Lead with the pre approval letter.
Bottom Line
Movers, housing office, school research. All of it can wait until you've got the right agent and the right lender lined up.
The buyers who win in Hampton Roads PCS season aren't the ones with the biggest budgets or the longest house hunting trips. They're the ones who built the right team before they ever started looking at houses. For veterans and active duty buyers, that team starts with a veteran agent who knows VA loans cold and a veteran loan officer who's been closing them for decades. That's the team you get when you call me.
When it's time to talk real estate, you know who to call.
If a PCS move is coming, everything I recommend is grounded in 441 closings across 13 years of Hampton Roads data, and you can browse my full set of Hampton Roads area guides.
About the Author
John King is a Navy veteran and licensed real estate agent with Berkshire Hathaway RW Towne Realty, serving Hampton Roads including Virginia Beach, Norfolk, and Chesapeake. Known for straightforward approach and market expertise. 📞 757-270-3994 📧 [email protected] 🌐 www.757King.com
Curious what your home is worth in today's market? Get a free home valuation and find out where you stand.
Related guides from John King
Written by John King, Navy veteran & REALTOR®, Berkshire Hathaway HomeServices RW Towne Realty · (757) 270-3994 · About John

Why these guides are different
Every article here is written by one local agent from his own transaction record, not by a content farm. The numbers below are the basis for the advice.
John King is a former Navy Machinist Mate and a licensed Virginia REALTOR® with Berkshire Hathaway HomeServices RW Towne Realty in Virginia Beach. Licensed since 2013, he has logged 441 closings across Virginia Beach, Norfolk, Chesapeake, Suffolk, Hampton, and Newport News, and specializes in military PCS relocation, VA loans, and waterfront property. He holds a 5.0 Google rating across 117 reviews and has earned the HRRA Circle of Excellence every year since 2015.
About John King See the transaction studyCommon questions about this library
Tap a question to expand it.
What is the Hampton Roads Real Estate Blog?
Which Hampton Roads neighborhoods are closest to each base?
How do VA loans work when buying in Virginia Beach or Norfolk?
What is the Hampton Roads real estate market like right now?
Should I buy or rent during a PCS to Hampton Roads?
Ready to talk about your move?
Reading is a good start. A 15-minute conversation with a local agent who has logged 441 closings in Hampton Roads is a better one.
Prefer to talk? Call or text John at (757) 270-3994.
441 Closings
Client-side closings across Hampton Roads since 2014.
189 VA-Financed Sales
Direct experience with military and veteran buyers.
270 Subdivisions
Experience spread across the whole region.

FOLLOW US


COMPANY
CUSTOMER CARE
LEGAL
Copyright 2026 John King | KingRealtor757. All Rights Reserved. Equal Housing Opportunity. REALTOR(R). Virginia License 0225211050.